
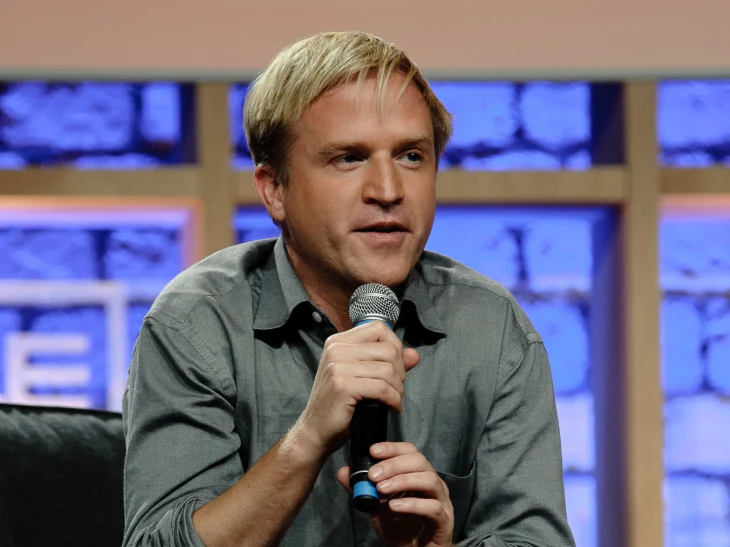
Matt Flannery is best known for helping build two very different financial-inclusion ventures. He co-founded Kiva, the nonprofit platform that helped make person-to-person microfinance familiar to internet users around the world, and later co-founded Branch International, a for-profit financial technology company focused on mobile financial services in emerging markets. The phrase Matt Flannery Entrepreneur captures only part of what makes his career interesting. His work sits at the intersection of software, lending, nonprofit innovation, storytelling, and financial access. Kiva and Branch pursue the same broad problem—people and small businesses being underserved by conventional credit systems—but they do so through different organizational models and very different relationships with capital. That contrast makes Flannery useful to study as a social entrepreneur. Kiva shows how a nonprofit can use technology and a community of individual lenders to expand access to relatively small loans. Branch represents a later phase in which mobile platforms and data-driven underwriting are used commercially. Neither model solves poverty by itself, but both demonstrate how software can change who is able to participate in financial systems.
From Stanford and TiVo to the First Kiva Experiment
Flannery studied at Stanford University, earning a bachelor’s degree in Symbolic Systems and a master’s degree in philosophy. That interdisciplinary background is more relevant to his later work than it may initially appear. Symbolic Systems combines areas such as computer science, psychology, linguistics, philosophy, and cognition, giving students experience with both technical systems and human decision-making. Before Kiva became a full-time venture, Flannery worked as a computer programmer at TiVo. He was not entering financial inclusion from a conventional banking career. His technical experience mattered because Kiva emerged at a moment when online payments, user profiles, and digital communities were making it possible to coordinate financial relationships across distance in ways that would have been much harder only a few years earlier. The Stanford Magazine — Early Kiva History recounts the early period when the project was still small and experimental. The broader idea developed as Flannery and Jessica Jackley became interested in microfinance and in the work of Muhammad Yunus and Grameen Bank. Jackley later spent time in East Africa meeting entrepreneurs who lacked access to conventional financing, while Flannery also spent time in the region documenting small-business stories. The key insight was not merely that poor entrepreneurs needed money. It was that the internet might allow ordinary individuals in one country to see the story of a specific entrepreneur elsewhere, contribute a small amount toward a loan, and then see that money repaid and potentially lent again.
Kiva Began Small Enough to Test Whether the Idea Worked
Kiva’s first pilot in 2005 involved only a small group of Ugandan entrepreneurs. That limited scale was a strength rather than a weakness. The founders were able to test the core behavior on which the entire model depended: would ordinary people actually lend small amounts online to entrepreneurs they had never met? The Stanford Graduate School of Business — Social Entrepreneurship: Kiva case material describes this early experimentation, while Kiva — History of the Platform traces the organization’s development from its initial pilot into a much larger international lending community. Kiva identifies its first funded loan as a $500 loan to Elizabeth, a fish seller in Uganda, in March 2005. She used the money to expand her business by buying more fish for resale. The details were modest, but the transaction contained the core idea of Kiva: a borrower had a specific productive need, many people could contribute small amounts, and repayment could allow the same capital to circulate again. Flannery initially worked on Kiva while still employed at TiVo, building the project during evenings before leaving his job in 2005 to focus on it full time. As online attention grew, the challenge quickly changed from proving that people would lend to figuring out how a small experiment could survive rapid demand.
What Kiva Actually Added to Microfinance
Kiva did not invent microcredit. Small-loan programs, cooperatives, microfinance institutions, and community lending systems existed long before the website. Muhammad Yunus and Grameen Bank had already made modern microcredit internationally prominent. Kiva’s innovation was to add an online crowdfunding and storytelling layer to those ideas. Individual borrower profiles made financial inclusion concrete. Instead of asking users to support an abstract program, Kiva let them see a person, an enterprise, a requested amount, and a purpose. That approach is examined directly in Stanford GSB — Kiva.org and the Power of a Story, which focuses on how narrative helped connect lenders with borrowers. Storytelling was not simply marketing decoration. It solved a comprehension problem. “Expanding access to capital” is an institutional objective; a profile of someone trying to buy inventory, equipment, livestock, education, or transportation gives the concept an immediate human form. At the same time, ethical storytelling requires accuracy, consent, dignity, privacy, and enough context to avoid reducing borrowers to simplified narratives of poverty. Kiva also lowered the participation barrier for lenders. Ordinary individuals could take part with relatively small amounts rather than needing to work through a bank, development agency, or specialized microfinance institution. Repayment created another distinctive feature: money that came back could often be lent again, giving supporters the experience of circulating rather than simply donating capital. That is why Kiva is related to charity but not identical to it. A donation is generally transferred without an expectation of repayment, whereas a Kiva loan is intended to be repaid under the terms of the particular lending structure, although repayment is never guaranteed. Readers interested in the communication side of charitable fundraising can compare that distinction with MyArticles’ guide on how to write a donation letter.
Technology Was Infrastructure, Not the Mission
Flannery’s technical background became increasingly important as Kiva grew. A successful platform had to display borrower profiles, accept and track many small contributions, coordinate payments, show funding progress and repayments, manage lender accounts, work with local partners, and maintain enough trust that people were willing to send money across borders. The website was therefore not the social mission by itself. It was infrastructure that made the mission scalable. This distinction is useful for understanding technology-based social entrepreneurship: a digital product matters because of the system of relationships it enables, not merely because the interface is innovative. Local institutions also remained important. An online platform in the United States could not independently evaluate every borrower in every country. Kiva has worked through a variety of lending partners and community structures, including microfinance institutions, nonprofit organizations, social enterprises, schools, and local groups. Those partners help identify borrowers, manage loan processes, and support repayment. The current Kiva — Current Lending Platform and Impact Statistics demonstrates how far the platform has moved beyond its first pilot, while Kiva — About and Current Impact describes the organization today as an international nonprofit focused on expanding financial access for underserved communities. The scale should not be confused with guaranteed investment performance: lending still involves repayment risk, local conditions, partner performance, and the design of individual programs.
Growth Forced Kiva to Become an Institution, Not Just a Startup
The earliest version of Kiva could be built around a small number of borrowers and a close founding team. Once demand grew, the organization had to deal with server capacity, legal compliance, payments, partner quality, identity and data issues, borrower protection, staffing, governance, and a much larger international operating network. The skills needed to launch the experiment were not identical to those required to manage a mature nonprofit. This is an important part of Flannery’s entrepreneurial story because founders often face a transition as organizations scale. Early-stage work rewards experimentation, product building, improvisation, and rapid problem solving. Mature organizations require formal systems, management layers, compliance procedures, long-term planning, and specialization. Flannery eventually stepped away from Kiva’s day-to-day executive leadership. That does not make the founding period a failure; it illustrates a common entrepreneurial reality. Some founders are especially effective at turning an uncertain idea into a functioning organization and then prefer to return to new product creation rather than spend the rest of their careers managing an established institution. Kiva’s influence also extended beyond microfinance. It launched before online crowdfunding became a mainstream internet category and helped demonstrate that large numbers of individuals were willing to make small financial contributions online when they understood the recipient and purpose. Later crowdfunding platforms applied similar digital mechanics to creative projects, products, charities, medical expenses, startups, and personal causes. MyArticles’ article on building a crowdfunding platform looks more directly at the platform-design side of that model. Branch International Took Flannery Into Commercial Fintech: Flannery co-founded Branch International in 2015, moving from nonprofit crowdfunding into a commercial financial-technology model. Branch International — Leadership lists him as co-founder and CEO. The company’s model is different from Kiva because it does not depend on a community of philanthropic lenders selecting individual borrower stories.
Branch developed around mobile-first financial services and the possibility of using software and alternative data to assess customers in markets where many people lack the conventional credit histories required by traditional banks. The underlying opportunity is straightforward: in many countries, mobile-phone access has spread faster than full access to bank branches, formal credit, and long-established financial records. A mobile financial platform can potentially accept applications remotely, evaluate applicants digitally, disburse funds without a branch visit, and collect repayments electronically. That can lower some of the cost of serving smaller transactions and reach customers outside major cities. But commercial fintech also introduces risks that a social-impact narrative should not ignore. Consumer protection, pricing, privacy, data use, cybersecurity, algorithmic decisions, and over-indebtedness all matter. Access to credit is valuable only when the product is suitable and the borrower can use and repay it under fair conditions. Kiva and Branch Show Two Different Routes to Financial Inclusion: The comparison between Kiva and Branch is more revealing than treating them as two versions of the same company. Kiva is a nonprofit that mobilizes a community of lenders and uses borrower stories to make small-scale finance accessible. Branch is a for-profit fintech company using mobile technology and data-driven systems to deliver financial services commercially.
| Dimension | Kiva | Branch International |
|---|---|---|
| Organizational model | Nonprofit | For-profit fintech |
| Core mechanism | Crowdfunded lending | Mobile financial services and digital underwriting |
| User relationship | Individual lenders support borrower loans | Customers interact directly with a financial platform |
| Role of stories | Central to lender engagement | Less central than data, product design, and underwriting |
| Shared problem | Limited access to conventional financial services | |
The shift from Kiva to Branch shows that financial exclusion can be addressed through more than one institutional form. A nonprofit can use community capital and social motivation; a commercial company can use technology, pricing, and scalable financial products. Each model has different incentives, risks, and responsibilities.
Why Credit Helps in Some Situations and Fails in Others
Microfinance has always attracted both strong support and serious criticism. Small loans can help borrowers invest in inventory, education, agriculture, equipment, transport, or emergency needs when conventional banks are unavailable. Access to finance can also help people establish records and participate more fully in formal economic systems. At the same time, credit is not a universal solution to poverty. Business outcomes vary, debt can become burdensome, and structural problems such as low wages, weak infrastructure, health shocks, discrimination, political instability, and limited markets cannot be solved by lending alone. A responsible account of Kiva or Branch should therefore avoid the claim that every loan automatically produces economic advancement. That is why impact should be measured through outcomes rather than loan volume alone. Useful questions include whether income improved, whether the business survived, whether financing replaced more expensive debt, whether the borrower gained greater autonomy, and whether repayment created harmful pressure. Scale is important, but it is not identical to social benefit. The distinction also explains why financial inclusion is broader than credit. Safe savings, payments, insurance, business financing, digital financial services, and a usable financial identity can all matter. Flannery’s career has remained centered on the problem of access, but the particular product used to expand that access has changed substantially. What Flannery’s Career Suggests About Social Entrepreneurship: Flannery’s career is a useful reminder that social entrepreneurship does not belong to one legal form. Kiva is a nonprofit; Branch is a commercial company. What connects them is the attempt to use entrepreneurial tools—technology, product design, new distribution systems, experimentation, and organizational innovation—to address a social problem. The Kiva story also demonstrates the value of starting with a test small enough to learn from. The founders did not begin by designing a system for millions of users. They tested whether a small number of borrowers could be funded by people in their personal network, observed what happened, and then built the infrastructure required by growth.
Trust was part of the product from the beginning. Financial platforms can have excellent software and still fail if users do not believe borrower information, payments, local partners, or reporting. Kiva’s use of stories helped create emotional connection, but the operational system behind those stories had to be credible enough to sustain repeat participation. Flannery’s interdisciplinary education also fits this pattern. Entrepreneurship in financial technology requires more than business-school concepts. Software architecture, human behavior, institutional trust, communication, and ethical judgment all affect whether a platform works. His move from philosophy and Symbolic Systems into programming, nonprofit lending, and fintech shows how those areas can intersect. A Career Built Around Repeated Institutional Experiments: Seen chronologically, Flannery’s career is less a sequence of unrelated jobs than a series of experiments in how technology can lower barriers to finance. At TiVo, he developed technical experience. With Kiva, that skill became part of a nonprofit platform connecting individual lenders with underserved borrowers. With Branch, the emphasis shifted toward mobile delivery and commercial financial services. The organizations are not interchangeable, and neither should be romanticized. Kiva still depends on lending structures, local partners, and borrower repayment. Branch operates in markets where digital credit creates real opportunities but also demands careful attention to consumer protection and data. The common thread is not “technology fixes poverty.” It is that technology can change the cost, scale, and accessibility of financial relationships. That is a more useful way to understand Flannery’s legacy than focusing only on founder mythology. His contribution lies in helping demonstrate that financial access can be redesigned institutionally: through online communities, small contributions, digital identity, mobile platforms, and new ways of evaluating and reaching customers who traditional systems often overlook.
Conclusion
Matt Flannery’s entrepreneurial career connects two phases of digital financial inclusion. Kiva helped popularize an online model in which ordinary individuals could support small loans to borrowers around the world, combining microfinance with internet payments, crowdfunding, and personal storytelling. Branch International later moved the same broad concern with financial access into commercial mobile fintech. The strongest lesson from his career is not that one platform can solve poverty. Credit carries risk, technology creates new forms of responsibility, and social impact has to be evaluated through outcomes rather than inspiring stories alone. What Flannery helped show is that entrepreneurs can redesign institutions around people whom established financial systems do not serve well. From a small Ugandan lending pilot to global nonprofit crowdfunding and then mobile financial services, his work has repeatedly tested the same underlying idea: access can change when technology lowers the distance between a financial need and the system capable of serving it.